Rule-based testing
Apply your exact entry, stop, and target rules against history instead of relying on hindsight or memory.
Define clear entry and exit rules, then step through real historical candles applying them exactly, using free chart replay. Record each test trade in the built-in journal to see, with real numbers, whether your strategy actually holds up.
Apply your exact entry, stop, and target rules against history instead of relying on hindsight or memory.
Add each test trade to the journal with New entry, so your results and notes stay in one place.
Backtest as many strategies and as many historical windows as you want, completely free.
Backtesting means testing a set of trading rules on past prices to see how they would have done. It’s the cheapest way of rejecting a bad idea. There are two main kinds. An automated backtest runs your rules through years of data in seconds and produces statistics. A manual backtest has you step through history yourself and apply the rules by hand.
The Tradeskill offers the manual kind, using chart replay. It doesn’t run automated strategies or generate a performance report for you. You step through real historical candles and record your test trades in the journal. It’s slower, but it trains your judgement in a way an automated test can’t.
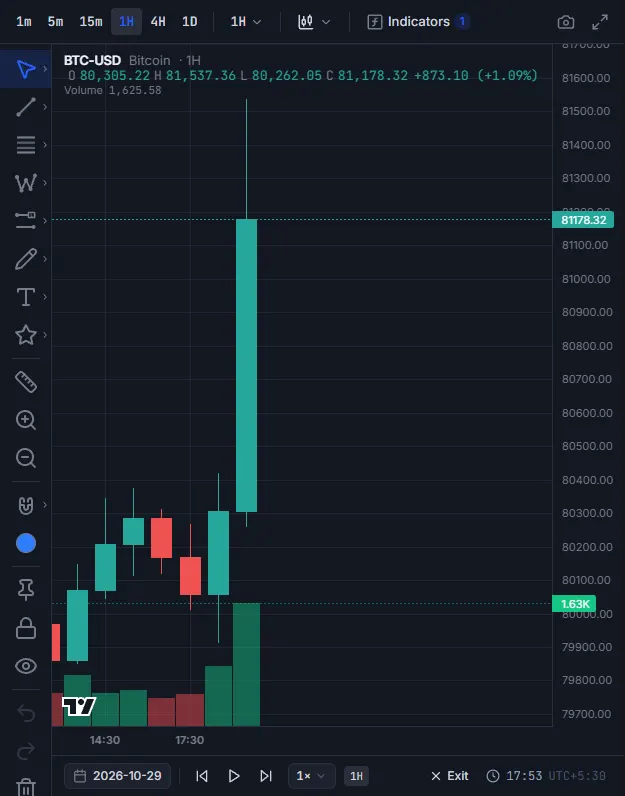
One thing to note: orders you place in the order ticket always use the live price, not the replay price. So record replay trades yourself rather than sending them through the ticket.
To show what honest results look like, we ran an automated test ourselves, outside the app, of a simple rule: buy when the 20-day average crosses above the 50-day, exit when it crosses back or when price falls two ATRs below entry, and pay 0.05% in fees each way.
| Period | Trades | Wins | Rule | Buy and hold |
|---|---|---|---|---|
| Bitcoin, Nov 2022 to Jul 2025 | 11 | 3 | +7.0% | +607.9% |
| Bitcoin, Jul 2025 to Nov 2026 | 5 | 2 | +6.4% | -33.6% |
| SPY, Feb 2021 to Dec 2024 | 8 | 1 | -9.0% | +54.6% |
| SPY, Dec 2024 to Oct 2026 | 2 | 1 | +13.9% | +25.2% |
The rule lagged holding in three of the four periods, though it avoided most of Bitcoin’s later fall. It also won only 7 of 26 trades. Testing just one period would have led you to the wrong conclusion, whichever one you chose. These are historical results and aren’t a recommendation.
A backtest tests the rule. Paper trading tests the rule and you. After a rule survives testing on history, try it live in the simulator with a realistic position size for a few weeks. If you can’t follow it when the next candle is unknown, the backtest result won’t help you. This is educational and isn’t financial advice.
For more depth, read our full step-by-step guide to backtesting a trading strategy on the blog, which covers this test in more detail.